- Home
- Storm Damage
- Roofing Insurance Claims
Roofing Insurance Claims: We Handle the Roof Side in Queens
Roofing insurance claims with Foundry Roofing run like this: we inspect the storm damage, build the photo report and repair estimate, meet your adjuster on the roof and do the approved repair. We handle claims on homes, co-ops, condos, apartment buildings, mixed-use and commercial roofs.
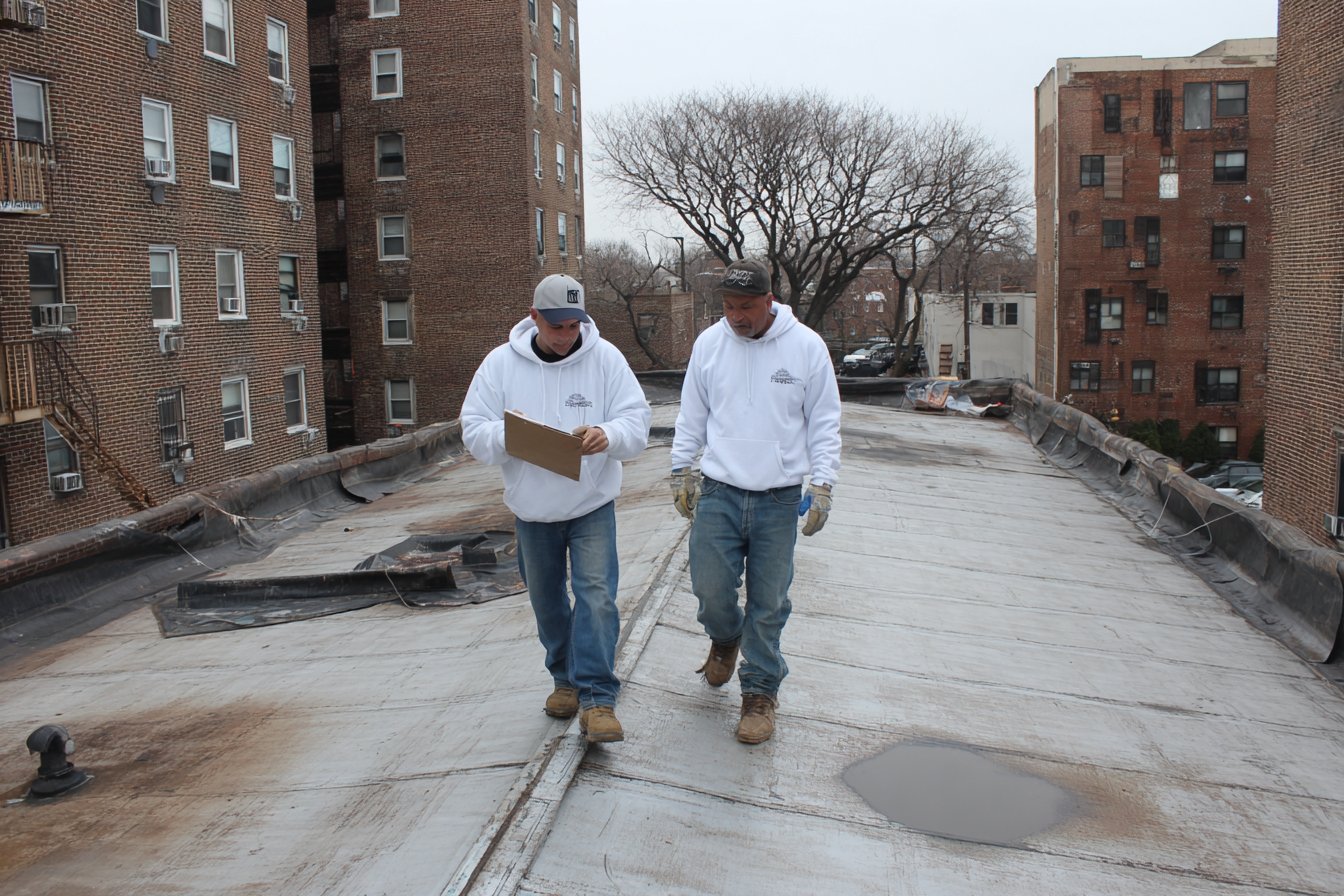 On the roof with your adjuster
Your claim, stage by stage
Each stage has our job and yours.
| Stage | We do | You do |
|---|---|---|
| After the storm | Tarp the open roof before the adjuster arrives | Photograph damage, notify your insurer |
| Our inspection | Damage assessment, dated photo report | Send it in |
| Adjuster visit | Meet the adjuster, walk every damaged area | Set the date |
| Scope of loss | Check it against our estimate, supplement missed items | Approve the scope |
| Repair | Storm repair, or replacing the roof once the claim approves it, plus a certificate of completion | Pay the deductible |
Who files, and whose policy responds
On roofing insurance claims, who files depends on who owns the building.
Co-op and condominium
The board or managing agent files under the master policy. We give the board a photo report to review and handle roof repairs for boards and associations.
Multi-family and apartment building
The landlord files. We schedule tenant access and log interior leaks unit by unit.
Commercial and mixed-use
Owner or tenant files, per the lease. We work around business hours.
Residential
You file on your property policy. We meet the adjuster so you stay off the roof.
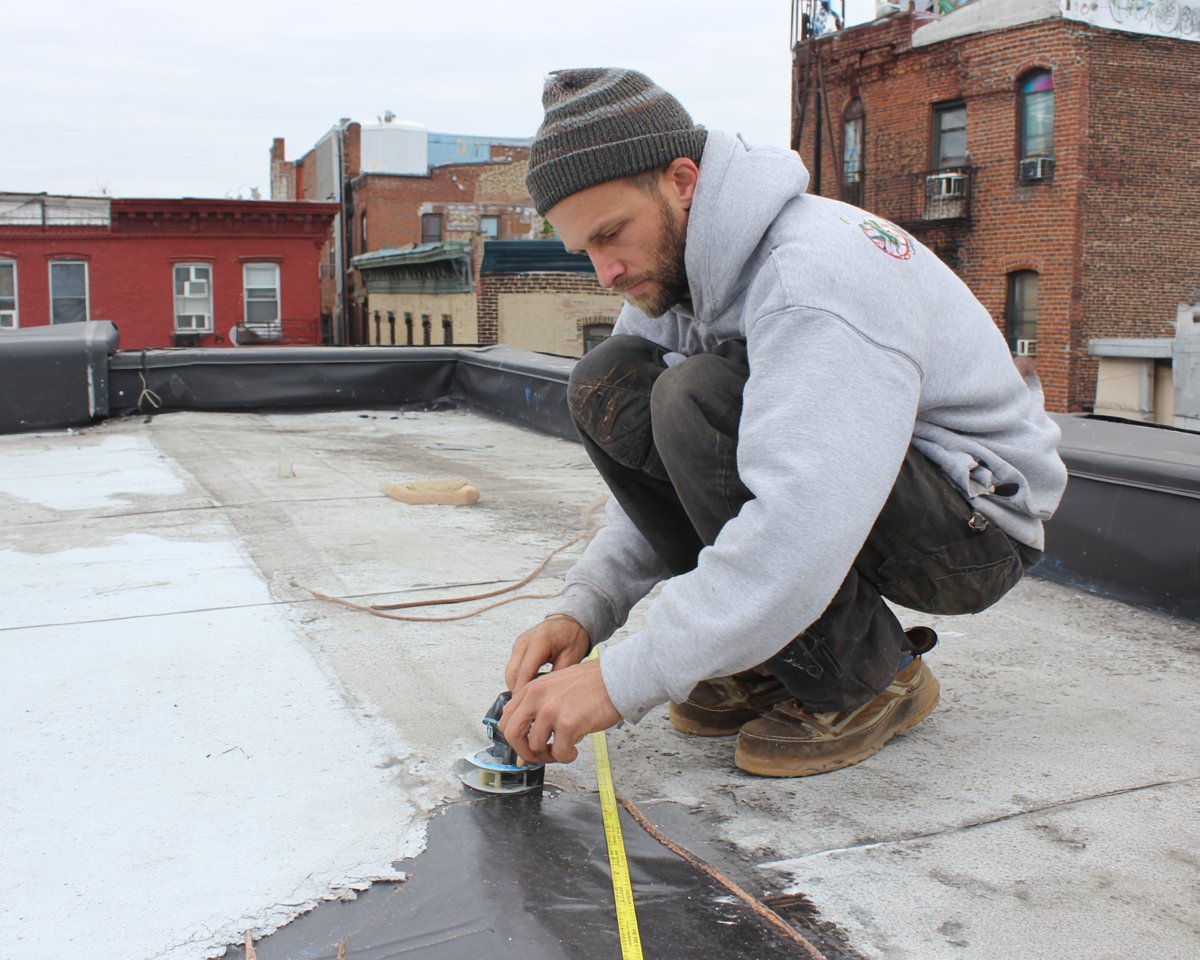 Re-inspection
When the insurer says no or pays short
Roof claims get denied or paid low when damage is logged as wear and tear, the cosmetic damage exclusion applies, or the scope of loss misses items.
We then read the denial letter with you, add photos and measurements, file a claim supplement and request a re-inspection with us on the roof. Severe hail can justify replacing a hail-damaged roof through insurance. If the damage is not storm-related, we say so, and you can decide on a repair without the claim.
Adjuster and paperwork questions
What do insurance adjusters look for on a roof?
Wind-lifted or missing shingles, torn membrane seams, hail bruising, granule loss, bent flashing and leaks matching the storm date.
What is the cosmetic damage exclusion?
It excludes damage that alters a roof's look but not its performance, such as dented metal panels.
What is a roofing certificate of completion, and does my insurer need it?
It is our signed confirmation that the approved work is done. Many insurers want it before final payment.
How do roofing companies work with insurance companies?
We document, price and walk the damage with your adjuster. The insurer decides coverage.
Get the damage on record before the adjuster visits
Book now and we photograph and measure the roof while the damage is fresh, so the report is ready on adjuster day.